
Simon Brown (00:07.96)
Worldwide markets this week shop right at highs, but is it offering value? I think it might well be. We’ve got FOMC and MPC, but inflation is looking ugly as petrol and diesel continue higher.
I’m Simon Brown, this is World Wide Markets, episode six hundred and ninety.
Simon Brown (00:56.992)
Summon Brown, this is Worldwide Markets episode 694 for 16 September. I am recording this late Tuesday afternoon. Worldwide Markets, powered by Standard Bank Global Markets, Retail, and Shyft, the global money app that puts travel, shopping, payments, and investments in the palm of your hand. Enjoy the cheapest forex rates anytime, anywhere. Shyft powered by Standard Bank. Thanks to Standard Bank. Thanks to Shyft.
let’s stay with them just a second. We have a power hour coming up this week. It is going to be Wednesday afternoon. sorry, Wednesday evening rather, 5:30. you can either attend in person, you can attend via the webcast. We’re gonna be talking CFDs. I think that’s an important point. We wanna focus on different CFDs and how they work. How do we implement CFDs? How do we use them? How do we manage the risk? Perhaps that’s a a key component on them. So we’ll look at
What they are, but also how do we manage risk? How do we use one percent rules? What are stop losses? All of those different parts, margins, the whole Shing Bang. 530 webcast or in-person at Rose Bank, just onelap.com/slash events for more information and booking.
Simon Brown (02:15.0)
Wednesday evening, eight o’clock, FAMC announcement on rates. the US tenure is above five percent. Everyone’s saying, it’s back in where it was in twenty twenty three. Yeah, it was there in twenty twenty three. Prior to that it was two thousand and eight. This is multi decade worst levels for the US tenure. It is the market saying to the US Fed, Treasury, whatever, the bond market is saying, Yeah, guys, we don’t believe you in your fight for inflation.
3.4% inflation number that came out for August, announced last week. That is putting in I mean, in their target of two percent, they haven’t been at in five years plus. I I I does the Fed still have credibility? This is the question, and I’m not sure that they do. So, will they or won’t they? Well, we know what Trump wants. we know what Walsh promised to do. We will see. The market is saying they have to hike.
quarter percent. And then next week is our own MPC. It’s happening on Wednesday, because Thursday’s a public holiday. and they held last time, a local MPC. But Kevin Lynx from Stanlib just tweeted earlier today. daily daily under recovery on SA petrol 364, in other words, expected jump. And on diesel 348 or 396, depending which you use, which means we’ve got a everything stays where it is, big change first week of October.
And I think if you were forecasting inflation a week ago, I don’t think you had those numbers in your mind. Two weeks ago. we’ve seen oil run higher. Trump is unable to end the war in Iran. and the the Iranians are saying they’re not in a hurry, they’re absolutely not in a hurry. So this is a mess, and I think we might get a hike from our own MPC next week, especially if we get one from the FOMC. So I think things are gonna start to get a little bit ugly in that regard. Inflation hasn’t gone away.
and I think we’re gonna see higher rates as well, which is just no fun whatsoever. But let’s move on to shop right. Disclaimer up front, I hold shop right shares. We had results out a couple of weeks ago. and my thoughts were it’s trading up at all time highs. And then the question is, well, okay, is there value? I like shares at all time highs. I like it to go where it’s never been before. And my thought was, well, is there some value? So I mean the the the the the short answer is.
Simon Brown (04:35.392)
Is that the stock’s done well over the last 12 months? It’s up some 15%. That’s not bad. But it’s also back where it was in November 2024. Can we call that two years ago? But over those two years, HEPS has gone from 1245 to 1527. In other words, that’s seen the the PE go from around 25 to around 20.5. That’s a 23% D rating. So you’ve got the same business making more profit at the same price.
Now there is a bear case. We delve into the bear case. Make no mistake about that. But I think there’s lots of bull case as well, potential for it. So just some numbers at a glance. We saw group revenue up seven percent, trading margin back at six percent. That’s the best in the world, to be clear. Diluted HEPS was up twelve point two, as was normal HEPS dividend per share up eleven point eight, eight grand seventy-three full year. That is slightly more than what I paid for my first shares about twenty years ago.
cash they’ve got 12.9 billion, it’s eight point one billion net cash. CapEx they’re spending a little under 7 billion. That’s two point two and a half percent of sales. Sales was 274 billion Rand. Giant, giant numbers. If we break it down, the the bigger you know, liquor’s doing well, what they’re adjacent businesses, and then 6060 are the big movers. So some important numbers that we need to look at. Internal selling price inflation, 0.8 percent.
and what we saw was against sort of national food inflation of 3.9%. Shop right had food inflation of minus 0.01%, you save minus 0.06. 11,500 items cheaper than a year ago. By shop by ShopRite’s calculations, that’s almost two billion of price given back to customers. I’ve said it before, I’ll say it again. Customers are aware of what ShopRite is doing. The the the five or ten rand meal.
At at ShopRite, the 40 Rand coffee and lunch at Checkers. you save doing a five Rand meal. The consumer knows that they couldn’t do that anywhere else, never mind at home. They know what ShopRite is doing. It’s loyalty. 1.3 billion store visits, and 9.3 billion items sold. I mean, staggering numbers, fun but meaningless. 262 new stores, and they’re gonna do another 254.
Simon Brown (06:58.646)
In the financial year 2027. That, if they do it, will take them over 3,000 stalls for the first time ever. Municipal charges, 19% higher. Electricity is now 2.3% of sales. And that’s with them moving big into renewable. So and a 5 billion buyback, and the trading margin, as I said, sitting at 6%. Really, really good numbers. So
Let’s focus on 6060 a moment. And I interviewed Peter Enabrecht a couple of weeks ago in my morning show. I asked him how many, how many customers on 6060 are not Checkers customers? And the answer is about half. So they do 1.1 million additional every week of via 6060. half of them are Checkers customers that they haven’t seen before. In other words, this is someone who is typically shopping at a Woolies, a Pick and Pay, and a Spa.
But suddenly comes to checkers, usually for convenience. That is half a million. That is a giant number. I mean, how many families do we have in South Africa? Eight or nine million households. That is absolutely it is a customer acquisition business for them, as much as all the other bits and pieces.
And they don’t many don’t use only one channel. When they’re in store, the spend is more than on 6060. Makes sense. 6060 is very much more a convenience. They talk around it being hugely profitable, but and and and they they don’t break out numbers beyond to say that it is profitable and to what the revenue is, but they don’t give huge numbers there. There’s some skeptical issues there. Only variable costs short. The store has
capacity. But once you’ve got a sort of a neat dedicated staff, dedicated space and time, dedicated stalls. And they have six dark stalls already, starts to change. Keith von Lacklin made a point recently on Moneyweb. you know, landlords want to check as there’s an anchor tenant to drive footfall. But if suddenly everyone’s going via 6060, well, they don’t want the scooters. I don’t think we’re at that point. Th the tension gets harder every year. I I appreciate that.
Simon Brown (09:02.712)
But I at that point I don’t think we’re there just yet. So 6060, 11.1% of supermarket RSA sales, 25.5 billion, operating out of 997 stores. That’s up by 303 stores. That’s because they added the shop right parts of it as well. takeout checkers and shop rights growing. Well, sorry, check out 6060 checkers brand about 4% growth.
With it added, it’s about 10%. So it’s worth about 6% of their their growth. Absolutely it is. and you know, to be clear, existing store sales growth in RSA supermarkets, 2%. Not much happening there at all. So the the the growth is coming from new space and that’s 60 60. I was gonna say we underestimate how powerful it is. I don’t think we do. It is absolutely insane. The the other point was, and I said this to Peter, because remember.
At the time of the results, they also announced they’re buying Vita Coffee and they’re buying RCA cellular or something like that. RNA cellular, sorry. And I said to him, Yo, Peter, I know what you’re doing. You’re looking down my credit card statement and you’re looking at everywhere where I spend money. And you’re saying I want Simon and everybody else to spend that money on his app. And what was his answer? 100% spot on. Absolutely, that is the point. That is what they want. And he says.
He wants to become our super app. He wants to sell us absolutely everything. He also said, and there’s an honest part, he says the economy is really not helping us. These days we are meddling in each other’s business. Telcos want to become insurers, retailers, banks, and so on and so on, because we’re all seeking growth. Imagine a three, four, five percent GDP growth. But so CEO is saying the core market’s not growing. Growth has to be manufactured by taking wallet share from adjacent industries.
Capitech into insurance, Vodacom into financial services, checkers into everything. So that is the super app, right. Groceries, liquor, pets, pharmacy, vitamins, general merchandise, white appliances, financial services, one basket, one checkout, one delivery, multiple entities. They’ve got the AI shopping assistant, which says it reaches 98% adoption amongst extra saving members within 90 days.
Simon Brown (11:22.124)
I haven’t used it. I I I said before I’m too close to my local checkers. I don’t use 6060. they call it agentic commerce. Whatever’s, it’s there. But the key point is that they are looking to get your market. And and and and coffee’s part of that, right? So they’re already what 400 Vita’s out there. We can see them. My local checkers has a Starbucks in it. gone. Sorry for you, Vita coming in.
We’re going to see more of that rolling out. You’re going to see Vita beans. You’re going to see Vita pods and everything like that. So to be clear, this is absolutely happening and they are a beast. And they really do want that one app where we can do absolutely everything. So what are the strengths? Deflation is a massive weapon when you’re a low-cost operator. And internalflation, 8% versus a 3.9 CPI, is a you can grab market share. And they have 80 plus months of growing market share. That is huge. Returns.
return on invested capital, 19.8%. They stated weighted average cost of capital, 11.5%. It’s an 8.3% point spread, which is why they open new stores because it makes money from day one. and they’ve also got both ends of the business. You save and shop right at the bottom, checkers and hyper at the top, boxes at the bottom, Woolies is at the top. No one else does this. So they kind of catch you at both ends. And 6060 really is a
It’s no longer a feature. It’s an absolute mode. 20,000 jobs, it’s a five year head start. You know, the rivals can copy it, but can they copy the fulfillment network? Can they copy store density, the data, what they know about us? that is gonna take years to catch up. And to be clear, Willie’s Dash, Pick and Pay, ASAP, SpartyU are all try, but they’re all multiple years behind. 24 billion of cash generation, absolutely massive.
And you know, in operator’s been there since twenty seventeen, in in various different guises, and we’ve got that management continuity. weakness, growth was slowing. sales was 7.2 down from 8.9, trading profit was 8.4 from 16.6, and HEPS was 12.2 from 15.8. Even 6060, 34.5% growth, to be clear, or for 20 billion odd business, that was down from 47.7.
Simon Brown (13:42.203)
is exist existing stores growing at two percent. Said that already, nothing much happening there. cost inflation, which is not under their control. Municipal charges up nineteen percent, electricity two point three percent of sales, no control over that. trading margin, they’re guiding still for six percent risk there. Acquisition risk. The acquisitions are small, but there’s always some risk there. But then opportunities. 6060 is only 11.1% of of supermarket RSA. Can that grow to 15, 20, 25?
Sure, I mean, why not? By a number of ways. If nothing else, they’re only in 997 stalls, which is about a third. That’s super app. It’s also, remember, financial services. The shop right wants to do banking. They want to bring way more into it. Extra savings has got Dartra on 30 million shoppers. they payments business. I mean, what they can do there, what Capitec and Time
If I were Capitech in time, I would be worried. Shopright already has money market, it has remittances, it has prepaid, but that’s a counter-service. Platform. Yo, stuff can happen here. The adjacencies, I like these businesses. They’re 1.9 billion out of 270. They are minute. They’re up 57% for the year. Pet shop, really important. They’re up to 185 stores, targeting 200.
Stores in a market that’s supposed to be worth 14 billion. Meteorite Plus up 67%. General merchandise up 66%. There’s a lot happening here. Outdoor clothing, liquor, all of that happening absolutely. there’s still market share. I think there’s still market share. And they’ve been growing, as I said, multiple, you know, for for 80 plus months of of market share growth. But spas currently struggling, pick and pay struggling and might have a strike. I went deep on pick and pay a few weeks ago. You can go look at that.
I think there’s still some market share. Threats. Well, the competitors. So Pick and Pay and Spa are both pretty much as bad as it can be. And let’s throw wollies into that as well. They’re pretty much as bad as it can be. The only way they can go is up. It’s going to take some time. Now, wollies, it’s the fashion for fashion, health, and beauty that is the problem. Not so much the food. But pick and pay and spa, as they start to improve.
Simon Brown (16:01.474)
They’re going to start coming for pick and pay for for shop right. They’re going to start coming for 6060. pick and pay also got an AI assistant called Penny. I think it runs off Gemini, which they released back, I think it was in July. so those two are absolutely coming for ShopRite. Make no mistake about that. Willie’s is already there in the top end. And then Boxer. And that’s one competitor that’s actually growing faster than ShopRite. Comparable margins and focusing at the USave and the ShopRite.
and it is doing well. So the broader threats is that competition will improve. they can’t get worse. They have to improve. 6060’s been directly attacked by Pick and Pay, ASAP, Penny, AI, Mr. D, the integrations there that’s happening, Takelot, Uber Eats, all of those, Amazon, dot Cozar, all of those. A five-year head start is great, but a five-year head start is not always a five-year head start.
deflation reverses, that’s a weapon that ShopRite can do because they can absorb it. I asked Peter about how they manage it. He says as long as we’ve growing volume, the producers don’t mind, but that’s a a risk. And of course, we have no GDP, minus 0.2 in the second quarter. Regulatory, yeah, and then execution always a risk. So the the big bets, I think, is the likes of of pet science, best of high margin.
Big business, lots of opportunity. Unique’s only 13 stores. I asked around. Everyone’s like, yeah, it it’s expensive. And Perel has really struggled with it. we want to watch the markdown rate more than anything. And that’s in person. I’ve got one just here. I’ll have a look-see. checkers outdoor, three stocks, three stores, immaterial. it really is a lexi. It’s got competing. I suppose Mr. Price Sports to a degree, Cape Union Mart. See how it goes. Little me, which is kids.
three stores folded, so actually shrinking. Lick is big, twenty one billion. it it’s only just behind sixty sixty. Midright moving, Vita, yeah, we’ll see R and A cellia and then financial absolutely. So
Simon Brown (18:07.884)
I think the key point to me is that we have an absolute beast of a business here. it is not massively expensive, particularly relevant. and here’s some fun numbers. So, shop rights market cap of around 170 billion. pick and pay, spa boxer willies combined is less than a hundred billion. I mean, that number just absolutely is is is is is is insane. It is cheaper.
than the profitable the than than than than the the the than boxer we can’t really compare it against pick and pay and spark because they’re lost making woolies is cheaper on a straight trailing pe boxer is more expensive so what’s priced in i think a lot is priced in i do think a lot is priced in but i do think it’s a business that is absolutely a machine can you buy it cheap yeah 260 bucks a little while ago the bull case so only retailer growing volume absolute amazing business
They can grow because their their earnings are their return on invested capital is almost twenty percent. Absolutely they can. the thing is all four, the bear case, all four competitors are off a low base. The share grain streak is gonna end sooner rather than later. That cannot carry forever and a day. Absolutely it can’t. There are some other issues, anchor tenant economics. it stalls into dark stalls. Where do they do that?
FY 57, sorry, FY27, current financial year, extra streak, extra week, so they can get an extra bit of revenue. Margin is flat, guidance is six percent, but that’s a giant number. so where does earnings growth come from? It’s gonna be stealing. What happens when they can’t still steal? I think that is absolutely a fair question. But to my point, this is not a stock that is expensive. It is
Trading. So the mean PE of the last decade is twenty-one. It’s at that level, but the forward is eighteen and a half, which is below the standard deviation, which is a nice chunky number there. Dividend yield of two point eight is not shabby. Price targets. So we’ve got six buys and two strong buys. We’ve got no hold sales or strong sales. low target three twenty-seven average, call it three fifty-eight and high is three seventy, stocks around three fourteen. It is cheap on all metrics, but if you look
Simon Brown (20:26.092)
At the guidance chart, it always seems to stick more than anything to the sort of low target. So I think it’s probably fully valued at this point in time. If we have a look at the chart, absolutely it is trading up at all time highs, back as I said, where it was late 2024, but with that extra earnings coming in. The point with is that ShopRite gives you opportunity. Where’s it coming back to?
I think it can easily get back to 290. Does it get back into the 260s? I’m not sure. But earlier this year, when it was trading in the 260s, on this very show and others, I was saying to folks, this is a cheap stock. We should be looking at it. You should be giving it some opportunity. And I do think so. I think at current levels, I think it’s fair value. But on any weakness, and you get back into the 300s, you get back into the 260s, I think it is really, really starting to look attractive in that regard.
So I think there’s definitely something worth having a look at here. It is a beast, as I said. I own it, and I’m a very, very happy owner in that regard. Let’s look at some stocks on the move that we’ve got a couple here on the we’ve got Netbank, outsurance, and Bitcorp. And on the down, we got Woolies, Absa, and let’s go look at clicks. let’s call some of these up. Let’s switch it across so that we can all be seeing the score.
Green. Last week, I should have mentioned at the top of the show. there was no show. I did record a show. I was in KZN. I was in Durban. I recorded it. There were technical problems. I threw it away. To be honest, I threw it away and went to the beach. so we did Netbank and ABSA a couple of weeks ago. NetBank is looking good, still trading just off all time highs, although a bit of a consolidation happening there. ABSA on the flip side. Where’s ABSA? There it is. ABSA.
Is looking weak and making lower lows and lower highs. Absol at current levels is frankly looking quite attractive. what else have we got? Woolies. Yo, yo, yo. Here is a stock that is not looking great at all. Woolies remains under pressure. and we are, where are we in terms of share price? Woolies at 36 Rand. We are back at pandemic levels, Feb 22. And if we take the pandemic out of the equation, we are back in 2012-ish.
Simon Brown (22:44.014)
2014 levels. That is pretty ugly. Another ugly one, clicks. Yup. I bought clicks because it was cheap and then it just went cheaper. Who knew? so where are we with clicks? I mean, it just keeps on falling. I’ve done the clicks story. you can go find I looked at clicks and Mr. Price. If there was any opportunity, was there a threat happening here? I think bits of both. I think clicks is great, I think clicks is cheap, and clicks just continues to be clear.
To get a whole lot cheaper. outsurance had some good numbers. Was it numbers or was it trading update? That’s when I go on holiday and I miss out on things. Outsurance looking nice. I move back to 75 gets industry. And then Bitcorp again, results recently. I didn’t get to chat to them. My show was too full. That’s just a messy looking chart all round. And then one, because I know everyone wants to know what’s happening with NASPASS. I don’t know what’s happening with NASPASS. I do know it’s falling like crazy and is not stopping.
I like NASPAS. It’s a good entry into the Chinese market. Ten cent. Yeah, I it it’s having a tough time of it, but I like it. Worldwide Markets, powered by Standard Bank Global Markets, Retail, and Shyft, the global money app that puts travel, shopping, payments, and investments in the palm of your hand. Enjoy the cheapest forex rates anytime, anywhere. Shyft, powered by Standard Bank. Thanks to Standard Bank. Thanks to Shyft. We’ll be back again next week. We have
Thirteen weeks until the end of the year. Well, with this show, twelve more to go. It’s about ninety odd sleeps. fifteenth of December as always will be my last. But mad rush. Until then, everyone, as always, look after yourself. We’ll chat again next week. If you can look after somebody else, my name is Simon. Have a good one. Cheers all.
Episode Summary
Shoprite is trading at all-time highs and it has still de-rated 23% in two years — same business, more profit, roughly the same price. Simon goes deep on the FY26 numbers, Sixty60’s shift from feature to moat, and the super-app land grab into coffee, pets, pharmacy and financial services. Before that: the US 10-year above 5% and a Fed with a credibility problem, and a South African fuel under-recovery big enough to change the inflation forecast.
Sponsored by Standard Bank Global Markets Retail & Shyft
What We Cover 🗂️
- 📉 The US 10-year above 5% — the bond market telling the Fed it does not believe the inflation fight
- ⛽ A 364c/l petrol under-recovery and 348–396c/l on diesel, landing in the first week of October
- 🏦 Why a hike from the FOMC on Wednesday could drag our own MPC with it next week
- 🛒 Shoprite at all-time highs: HEPS from 1245c to 1527c, PE from ~25 to ~20.5
- 🛵 Sixty60 at 11.1% of RSA supermarket sales — and half its weekly customers are new to Checkers
- ☕ The super app: Vida e Caffè, cellular, Petshop Science, Medirite Plus, banking ambitions
- ⚠️ The bear case — every growth line slowing, and four competitors off a low base
- 📊 Stocks on the move: Nedbank, OUTsurance, Bidcorp up; Woolworths, Absa, Clicks down
Key Takeaways 💡
- Shoprite has de-rated while going up. The share is up ~15% over 12 months and back where it sat in November 2024, but HEPS moved from 1245c to 1527c over that stretch. The PE fell from roughly 25 to 20.5 — a 23% de-rating on a business that got better, not worse.
- Deflation is a weapon, not a problem, if you are the low-cost operator. Internal selling price inflation of 0.8% against national food inflation of 3.9%, with Shoprite food inflation at -0.01% and USave at -0.06%, and 11,500 items cheaper than a year ago. That is roughly R2bn handed back to customers — and 80-plus consecutive months of market share gains.
- Sixty60 is no longer a feature. R25.5bn of sales from 997 stores, 11.1% of RSA supermarket sales, and about half of the 1.1 million extra weekly customers had not shopped Checkers before. Rivals can copy the app; the fulfilment network, store density and data take years.
- The returns math explains the store roll-out. ROIC of 19.8% against a stated WACC of 11.5% is an 8.3 percentage point spread — new stores make money from day one. 262 opened this year, 254 planned for FY27, taking the group past 3,000 stores for the first time.
- Fair value here, attractive on weakness. Ten-year mean PE of 21 with the share on that level and a forward of 18.5, dividend yield 2.8%, and a broker low target of 327c against a 314c share price. Simon rates it fully valued at current levels and interesting back in the 290s, compelling in the 260s.
- The bear case is real. Every line slowed: sales 7.2% from 8.9%, trading profit 8.4% from 16.6%, HEPS 12.2% from 15.8%, Sixty60 34.5% from 47.7%. Existing-store sales growth in RSA supermarkets is 2%. Growth is being taken from competitors — and all four of them are off a low base with nowhere to go but up
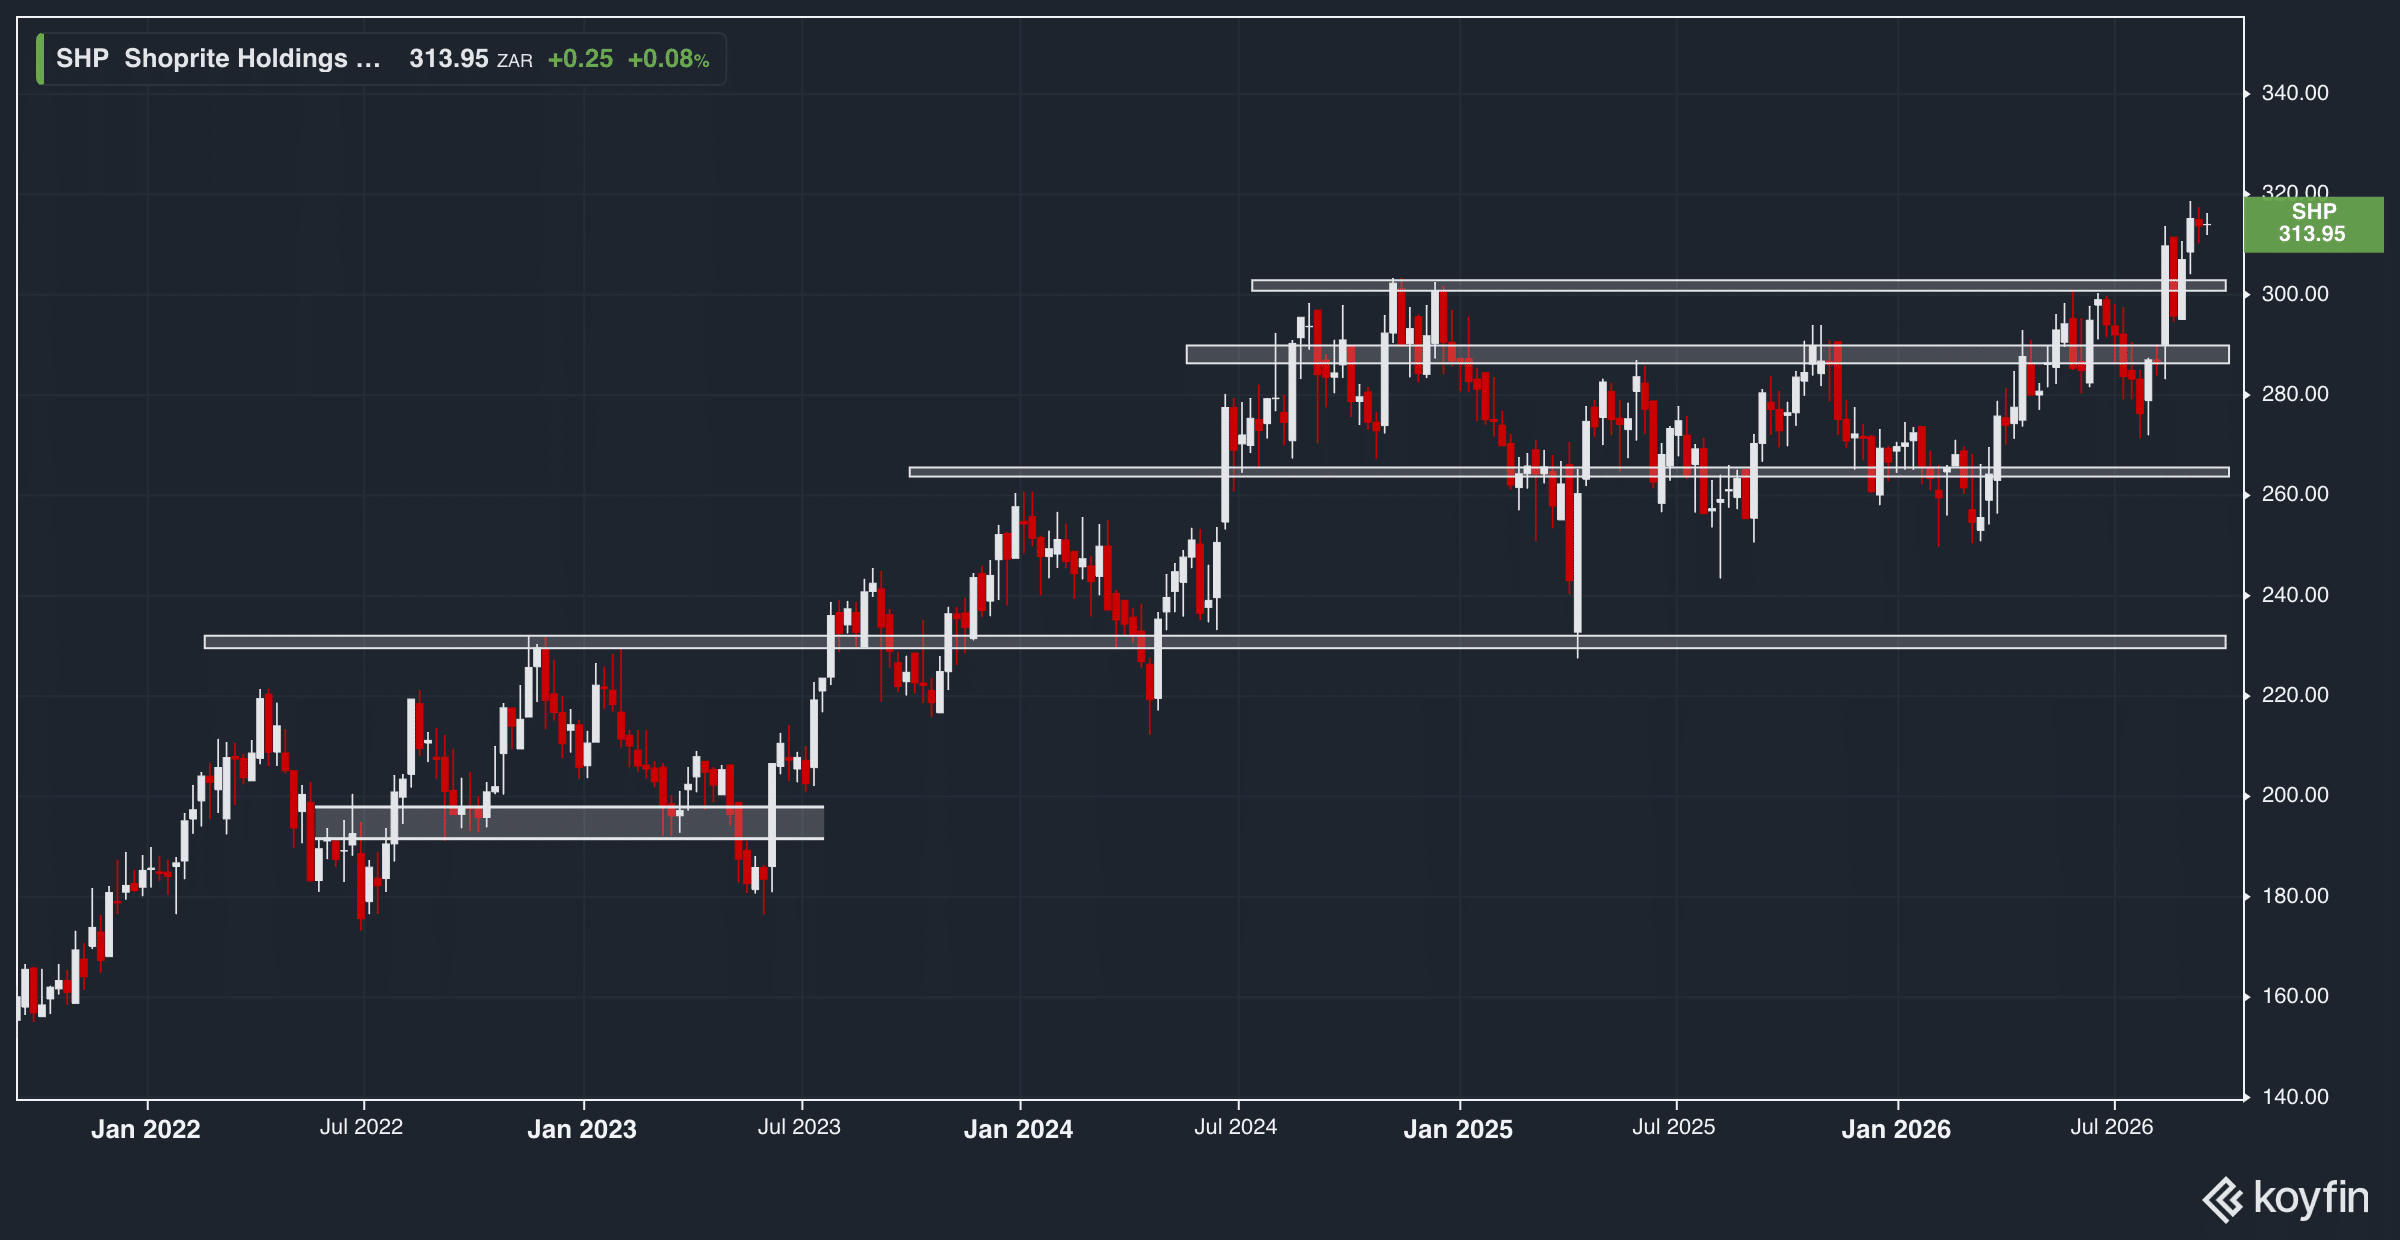
Shoprite weekly chart
All charts by KoyFin | Get 10% off your order

Wednesdays are all about hard-core investing and trading with Simon Brown’s WorldWide Markets podcast (previously JSE Direct). JSE Direct started life on ClassicFM in July 2008 and became a podcast in 2011. Every week Simon shares his views on the state of global economies, individual shares and events moving markets.
Contact Simon
More about Simon


